Checking Prices Without Obsessing
Checking a price constantly does not produce better decisions, it produces more decisions, and most of them are worse. A trader who spent roughly a year monitoring Counter-Strike [CS] skin prices multiple times a day found that frequency, not information, was driving nearly every bad call: buying into short-lived upticks and selling into routine dips that recovered within weeks. The fix was not to stop tracking but to compress it into one scheduled weekly review, a short midweek check only when a decision was pending, and a price ceiling set in advance for anything on a watchlist. That structure, not more vigilance, cut the error rate. The broader lesson applies well beyond virtual goods: any market, portfolio, or recurring business decision exposed to constant monitoring is vulnerable to the same trap, where checking more often feels like diligence but functions as noise amplification.
Why does checking a price more often lead to worse decisions, not better ones?
Most of what shows up during frequent checking is short-term noise rather than a real shift in supply or demand, and in the moment it is nearly impossible to tell the two apart, so frequent checking mainly increases the number of chances to react to noise.
What two decision patterns tend to repeat when someone monitors prices constantly?
Buying into a short uptick on the theory that waiting will cost more, and selling into a routine dip out of fear it will keep falling, both driven by how often the price was checked rather than by any real view on the asset.
How much time does a disciplined weekly price-review routine actually require?
In the case described, the full routine took about 10 minutes a week, plus a short extra check after a notable event such as a new product release that affects the watched items.
What is a watchlist, and why does it replace open-ended browsing?
A watchlist limits review to a short, defined list, items already owned and worth selling, or items wanted with a price ceiling already set, so everything else is simply not reviewed rather than browsed out of habit.
Why does setting a price ceiling in advance matter more than watching the market closely?
Deciding a maximum acceptable price before looking removes the emotional pull of a listing that feels urgent in the moment, since a price above a pre-set ceiling is simply not a candidate, regardless of how compelling it feels at that moment.
What role does fear of missing out play in frequent price checking?
Fear of missing out makes a missed opportunity feel like a loss already taken, which pushes people to decide in the moment rather than against a threshold set in advance, and that in-the-moment pressure is largely absent once a ceiling already exists.
Why does price history matter more than a single current price figure?
A single number reveals almost nothing about whether a move is likely to persist, while a history of price movement over time gives enough context to judge whether a current price sits inside or outside its normal range.
Does switching to a scheduled routine make someone better at predicting price moves?
Not necessarily, the routine does not improve forecasting accuracy, it reduces the number of decisions made from reaction alone, which is a different and more reliably achievable goal.
Why is a bad decision made under a disciplined routine less costly than one made from constant monitoring?
A decision made against a pre-set ceiling and a scheduled review can be explained and learned from afterward, while a decision made from an in-the-moment reaction to hourly price movement usually cannot be traced back to any reasoning at all.
Does this lesson about disciplined monitoring apply only to virtual goods markets?
No, the same dynamic applies to any market, portfolio, or recurring business decision where constant access to a number creates pressure to act on it, from stock tickers to daily sales dashboards.
A trader who followed Counter-Strike [CS] skin prices for about a year checked them more often than personal messages, often while a match loaded, while waiting in line, and occasionally well after midnight for no reason that held up the next morning. The habit had nothing to do with the size of the collection being monitored, a modest set of mid-tier rifle finishes that were actually being used rather than held for resale. The behavior resembled someone managing a large, actively traded portfolio requiring hourly attention, when the actual stakes did not justify anything close to that level of vigilance. That gap between the size of the stakes and the intensity of the monitoring is the starting point for a wider lesson about how constant access to a price, a metric, or a dashboard changes behavior independent of whether the underlying situation has changed at all.
The Habit That Creeps In Quietly
The tracking started for a defensible reason. Before buying an AK-47 | Slate, the trader wanted a sense of its fair value, so a cs skins market page got opened, a handful of listings got compared, and a reasonable price range emerged. That initial research was genuinely useful, the mistake was never closing the browser tab afterward.
Within a few weeks, the trader could recite daily price movement on six or seven items without looking anything up, checking before and after nearly every match. A two percent move on any given day started to carry an emotional charge entirely disproportionate to its actual significance. At that point, tracking had stopped functioning as research and had turned into something closer to a mood regulator tied to numbers that mostly were not moving for any real reason.
The inventory itself had not changed during this period, only the level of attention paid to it had. That distinction matters because it isolates the actual variable at work: not the asset, not the market, but the frequency of checking itself. Separating the two, what the asset is doing versus how closely someone is watching it, is the first step toward recognizing when monitoring has crossed into compulsion rather than diligence.
Why Constant Monitoring Erodes Decision Quality
The working assumption behind frequent checking is that more information produces better timing. Research on individual investors suggests the opposite happens in practice, the most frequent traders in a large sample of brokerage accounts earned substantially lower annual returns than less active traders over the same period, a gap large enough to erase most of any advantage that extra information was supposed to provide.1 Most of what shows up during frequent checking is market noise, routine daily movement unrelated to any real shift in underlying supply or demand, and in the moment it is nearly impossible to separate the two.
Two patterns repeated in the CS skin tracking described above, and both are recognizable well beyond gaming markets.
- A skin ticked upward for three straight days, and the trader read that as the start of a larger move, paying a price that would have been refused a week earlier, reasoning that waiting would only cost more
- A finish the trader genuinely liked had a weak week, prompting a sale into that temporary weakness, only for the price to recover within a month while the position sat empty
Neither decision reflected an actual view on the item's value. Both came from having looked too often, and frequency was the one variable fully within the trader's control throughout the entire period. Markets with large numbers of participants trading on incomplete information rather than careful analysis tend to generate exactly this kind of short-term movement, which is precisely the signal that frequent checkers mistake for meaningful change.2
A Disciplined Routine Beats Constant Checking
The fix was not abandoning price tracking altogether. Knowing an inventory's worth, and knowing when a wanted item has moved into an acceptable range, remained genuinely useful goals. What changed was giving that checking a fixed time and a fixed shape instead of letting it run continuously in the background all day.
The resulting schedule took about 10 minutes a week in total, with a short additional check added only after a notable event affecting the watched items.
| When | What gets reviewed |
|---|---|
| Once a week | A full pass over the watchlist and anything planned for purchase |
| Midweek, five minutes | Only items with an active decision pending |
| After a major release | One extra pass limited to the items it affects |
| Every other moment | Nothing |
Compressing the checking into fewer sessions also addressed a separate problem that constant monitoring creates on its own, a measurable decline in judgment quality that builds across a long string of repeated decisions over the course of a single day.3 The second structural change was building a watchlist to replace open-ended browsing entirely. Only two categories of item earned a place on it, items already owned that might be sold, and items wanted where a price ceiling had already been set. Everything outside those two categories counted as entertainment browsing, and entertainment browsing was precisely how the original habit had taken hold in the first place.
Why Setting A Ceiling Matters More Than Watching Closely
Setting a price ceiling before looking turned out to be the single most effective change in the entire routine. Deciding in advance that a Field-Tested rifle finish was worth no more than $80 meant a listing at $90 simply fell outside consideration, with no debate required in the moment it appeared. Committing to a threshold ahead of time functions the same way a pre-commitment device works in behavioral economics more broadly, removing a future decision from the moment of greatest temptation and placing it instead at a calmer point when judgment is less compromised.4
Deciding in the moment, rather than against a pre-set threshold, is exactly where Fear Of Missing Out (FOMO) does the most damage, because a missed opportunity starts to feel like money already lost even though nothing was actually spent. That feeling is not a minor side effect, it is the mechanism that pulls a disciplined watcher into an undisciplined purchase. The ceiling works precisely because it was fixed before that feeling had a chance to form, not because the watcher became more resistant to it in the moment.
A related bias compounds the problem for anyone comparing a current price against where it stood a day or an hour earlier. People tend to rely too heavily on the first number they see when judging whether a later number is reasonable, a tendency well documented in negotiation and pricing research, which means a price that has simply returned to its normal range can still feel like a bargain if the comparison point was an unusually high anchor from recent memory.5
The Right Tool Still Needs The Right Habit
A weekly review only works if a single sitting can deliver the full picture needed to make a decision. That requirement shaped which platform suited the new routine. Items placed on a watch list could be revisited directly, and each one displayed price history rather than a single current figure that, on its own, says very little about whether a move is likely to hold.
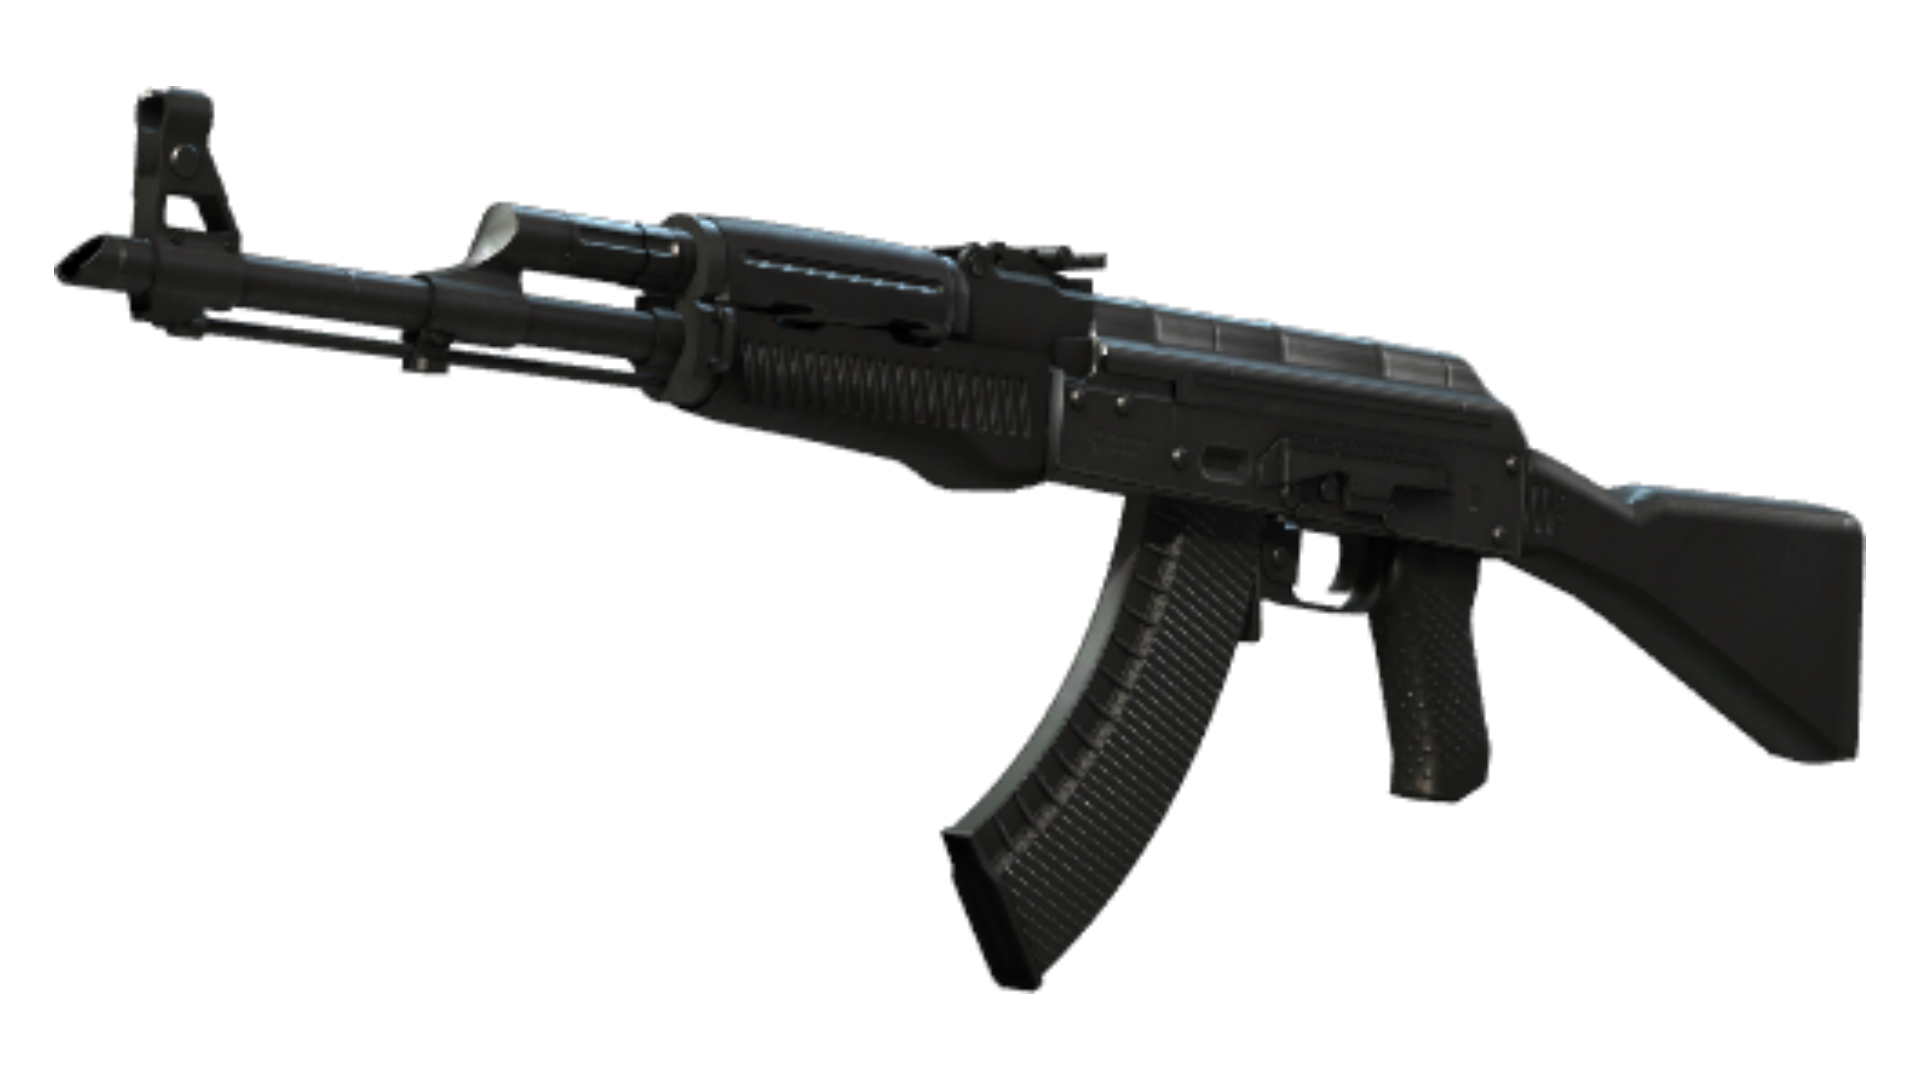
Price history provides meaningfully more context than any single day's price, though it still cannot guarantee that a given move will last. Filtering listings by exterior condition and Float Value matters for the same underlying reason, since two listings sharing a name are not always genuinely comparable, a distinction that daily checking never resolved regardless of how often it was repeated. A specific listing for an AK-47 | Slate illustrates the point well, since its price depends heavily on exterior wear and float value rather than on the name alone.
None of this makes the routine a better forecasting method. It does make the person running it meaningfully less likely to act on nothing, which is a different and more durable improvement than predictive accuracy would have been.
What The Routine Actually Changes
Results after switching to the scheduled approach were not dramatically different in aggregate, the mix of good and bad calls stayed roughly the same as before. The meaningful difference showed up in whether each decision could be explained afterward. A bad call made against a pre-set ceiling and a scheduled review is one that can be traced back to specific reasoning, even when that reasoning turns out to be wrong. A bad call made from hourly monitoring rarely has any reasoning behind it at all, since it was a reaction to a number rather than a judgment about value.
The practical payoff was mostly reclaimed time rather than improved returns. Markets followed out of genuine interest remain more enjoyable when they do not also demand constant supervision to feel manageable. The version of that interest requiring hourly updates was measurably less enjoyable than the version built around a 10-minute weekly review, a fixed ceiling, and a watchlist that filtered out everything else as simple entertainment rather than a decision waiting to be made.
The same structure applies directly to business contexts far removed from virtual goods trading. A sales dashboard checked every hour, a stock position reviewed between every meeting, or a competitor's pricing page monitored daily all create the same trap, mistaking frequency for diligence and reaction for analysis. Scheduling the review, capping how often it happens, and fixing a threshold before looking are changes any decision-maker facing a constantly available number can apply, regardless of what that number happens to measure.
The results of switching to a scheduled routine were not dramatically better, the mix of good and bad calls stayed roughly the same. What changed was the quality of the reasoning behind each decision. A bad call made from a pre-set ceiling and a weekly review is explainable after the fact, while a bad call made from hourly monitoring usually is not, because it was never really a decision, it was a reaction. The hours spent watching prices move were not generating insight, they were generating anxiety dressed up as attentiveness. Scheduling the review, capping its frequency, and fixing a price ceiling before looking are the three changes that separate monitoring from obsessing, and they transfer directly to any environment where constant access to a number creates the illusion that watching it is the same as managing it.
Citation
Cite this article
Sridharan, M. A. (2026, October 5). Checking Prices Without Obsessing. Think Insights. https://thinkinsights.net/community/checking-prices-without-obsessing (Accessed [[ACCESS_DATE]])
Sridharan, Mithun A. "Checking Prices Without Obsessing." Think Insights, 5 Oct. 2026, https://thinkinsights.net/community/checking-prices-without-obsessing. Accessed [[ACCESS_DATE]].
Mithun A. Sridharan, "Checking Prices Without Obsessing," Think Insights, October 5, 2026, https://thinkinsights.net/community/checking-prices-without-obsessing. Accessed [[ACCESS_DATE]].
Sridharan, M.A. (2026) 'Checking Prices Without Obsessing', Think Insights. Available at: https://thinkinsights.net/community/checking-prices-without-obsessing (Accessed: [[ACCESS_DATE]]).
M. A. Sridharan, "Checking Prices Without Obsessing," Think Insights, 2026. [Online]. Available: https://thinkinsights.net/community/checking-prices-without-obsessing. [Accessed: [[ACCESS_DATE]]].
Sridharan MA. Checking Prices Without Obsessing. Think Insights. Published October 5, 2026. Accessed [[ACCESS_DATE]]. https://thinkinsights.net/community/checking-prices-without-obsessing
Test Your Knowledge
Checking Prices Without Obsessing
Challenge yourself on the concepts from this article and see how well you understood them.
Subscribers get weekly quizzes and insights — subscribe free
Sponsor this article
Partner with Think Insights
Reach 50,000+ business leaders, consultants, and strategists. Feature your brand alongside expert articles on strategy, leadership, and digital transformation.
Become a Sponsor